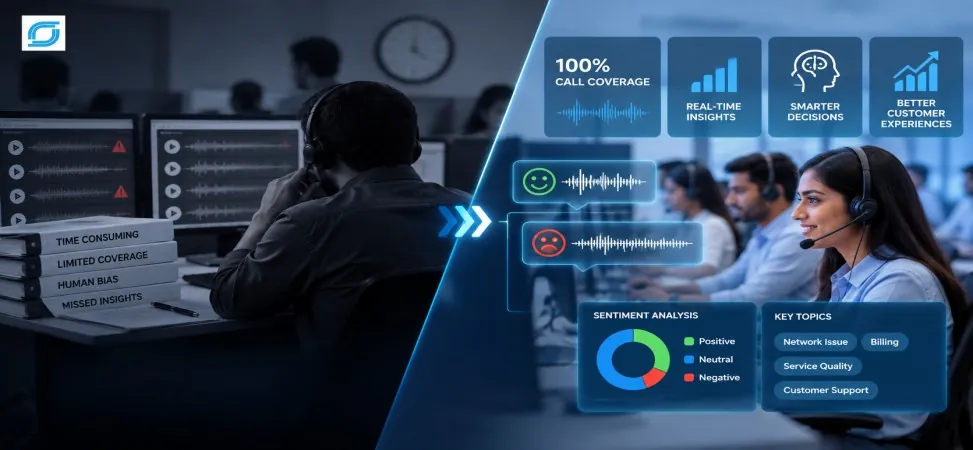
How behavioral science helps telecom carriers design repayment plans that subscribers finish — lifting completion rates to 70–85%, versus the 40–55% industry norm.
In first-party telecom collections, the hard part isn’t getting a subscriber to agree to a payment plan. Agents do that well. The problem comes next. Between 45% and 60% of telecom payment plans are abandoned before they’re paid off. The subscriber makes two or three payments, then stops. The debt goes back into the collections queue, and the whole process starts over — at extra cost, with a subscriber who now trusts the carrier even less.
That’s why more first-party teams are rethinking how they build these plans. The fix isn’t harder negotiation. It’s better design, grounded in behavioral science.
Repayment plan design applies behavioral science to the structure of a payment plan. The goal isn’t just to win a commitment. It’s to help the subscriber finish. People abandon plans for predictable reasons: the first payment feels too big, the timeline feels too far off, and they never see progress. Once you understand those triggers, you can design plans people are equipped to complete. Research on behavioral nudges backs this up — small changes to how a choice is framed produce real, cost-effective results in financial decisions.
Repayment design works alongside the rest of the collections toolkit — intervening early on at-risk accounts, digital-first predictive collections, and rich messaging that nudges repayment.
Why Standard Payment Plans Fail
Most payment plans are built for administrative convenience, not for the person paying. They split the balance into equal monthly installments over a fixed term. That ignores how people behave. The first payment feels heavy because it’s the same size as every other one — there’s no easy way in. The timeline often runs past how far ahead a subscriber plans, so the commitment feels abstract. And there’s no way to see progress, so the finish line never feels closer.
Standard vs. Behaviorally Designed Payment Plans
Five Principles Behind Plans That Get Finished
Behaviorally designed plans rest on five principles. Each one fixes a specific reason standard plans fail.
Start small. Make the first payment smaller than the rest. A subscriber who commits to a $15 first payment is far more likely to keep paying $40 a month than one who faces $40 from day one.
Match payday. Schedule payments a day or two after the subscriber usually gets paid. That alone cuts missed payments from empty accounts.
Show progress. After each payment, send a quick message with the updated balance and percent complete. Seeing the finish line get closer keeps people going. Meta-analyses of nudge interventions show these small prompts have measurable effects.
Frame the loss. In reminders, lead with what the subscriber stands to lose — their progress, their service — not with what the carrier will do. Loss is two to three times more motivating than an equal gain.
Reward completion. Offer something concrete for finishing, like a waived late fee or a one-month service credit. It makes the last payment worth reaching.
“Payment plan design is not an administrative task. It is a behavioral engineering challenge. When you structure the plan around how subscribers actually make financial decisions, completion rates rise from 45% to 80%. The debt is the same. The psychology is completely different.” — Behavioral Economics in Collections, 2026
Training Agents to Build the Right Plan
Good plan design depends on agents who can read a subscriber’s real situation and build around it. Sequential Tech trains first-party collections agents to spot income cycles, structure plans to a real budget, and ask the questions that reveal what someone can actually pay — not the most they can be pushed to promise. Industry analysis from Experian points the same way: automation plus personal engagement lifts recovery and lowers compliance risk.
Delivered across two segments and two centers for a leading US wireless operator.
Design Payment Plans That Subscribers Actually Complete
As part of our telecom collections services, Sequential Tech designs repayment plans around how people really make financial decisions — lifting completion rates from 45% to over 80%. Trained agents, proven behavioral principles, and progress-driven structure mean every plan is built to finish, not just to start.